
Primary or Secondary Market: Where to Start
The primary market refers to the first purchase of a property from a developer, while the secondary market means buying from the current owner. The better option depends not on price alone, but on your goal, timeline, budget, and the level of risk you are prepared to accept.
This guide is intended for buyers from Poland and other EU countries who are considering purchasing property abroad for personal use, as a second home, for rental purposes, or as part of a capital preservation strategy. If you are wondering what type of property to buy, it is worth starting by defining how you plan to use it and your investment horizon.
A new-build property may be better suited to someone looking for modern standards and a development designed with rental in mind. A resale property may be the right choice when the priority is a specific, established location and the ability to take possession quickly. When purchasing property abroad, ownership rules, taxes, the form of the contract, and payment protection mechanisms should always be verified in the relevant jurisdiction.
MAG World Properties focuses on primary-market properties from verified developers. We help clients compare them with available alternatives based on their individual goals rather than following a one-size-fits-all approach.
Primary vs Secondary Market — Key Differences
The differences between the primary and secondary markets are best assessed at the level of a specific city, district, and country. A new apartment in a developing part of a city may require waiting for completion, while a new-build and a resale property in the same central location may have completely different cost and availability profiles.
|
Criterion |
Primary Market |
Secondary Market |
|
Seller |
Developer or entity responsible for the project |
Current owner |
|
Property condition |
From developer standard to a fully finished apartment |
Actual condition visible during the viewing |
|
Possession date |
Immediately or after construction is completed |
Often sooner, depending on the agreement |
|
Customisation |
Usually greater before handover |
Limited; may require renovation |
|
Risks to verify |
Schedule, project quality, payment protection |
Technical condition, ownership title, encumbrances |
|
Location |
Often new districts and developments |
Frequently established, well-known neighbourhoods |
What Does the Primary Market Mean?
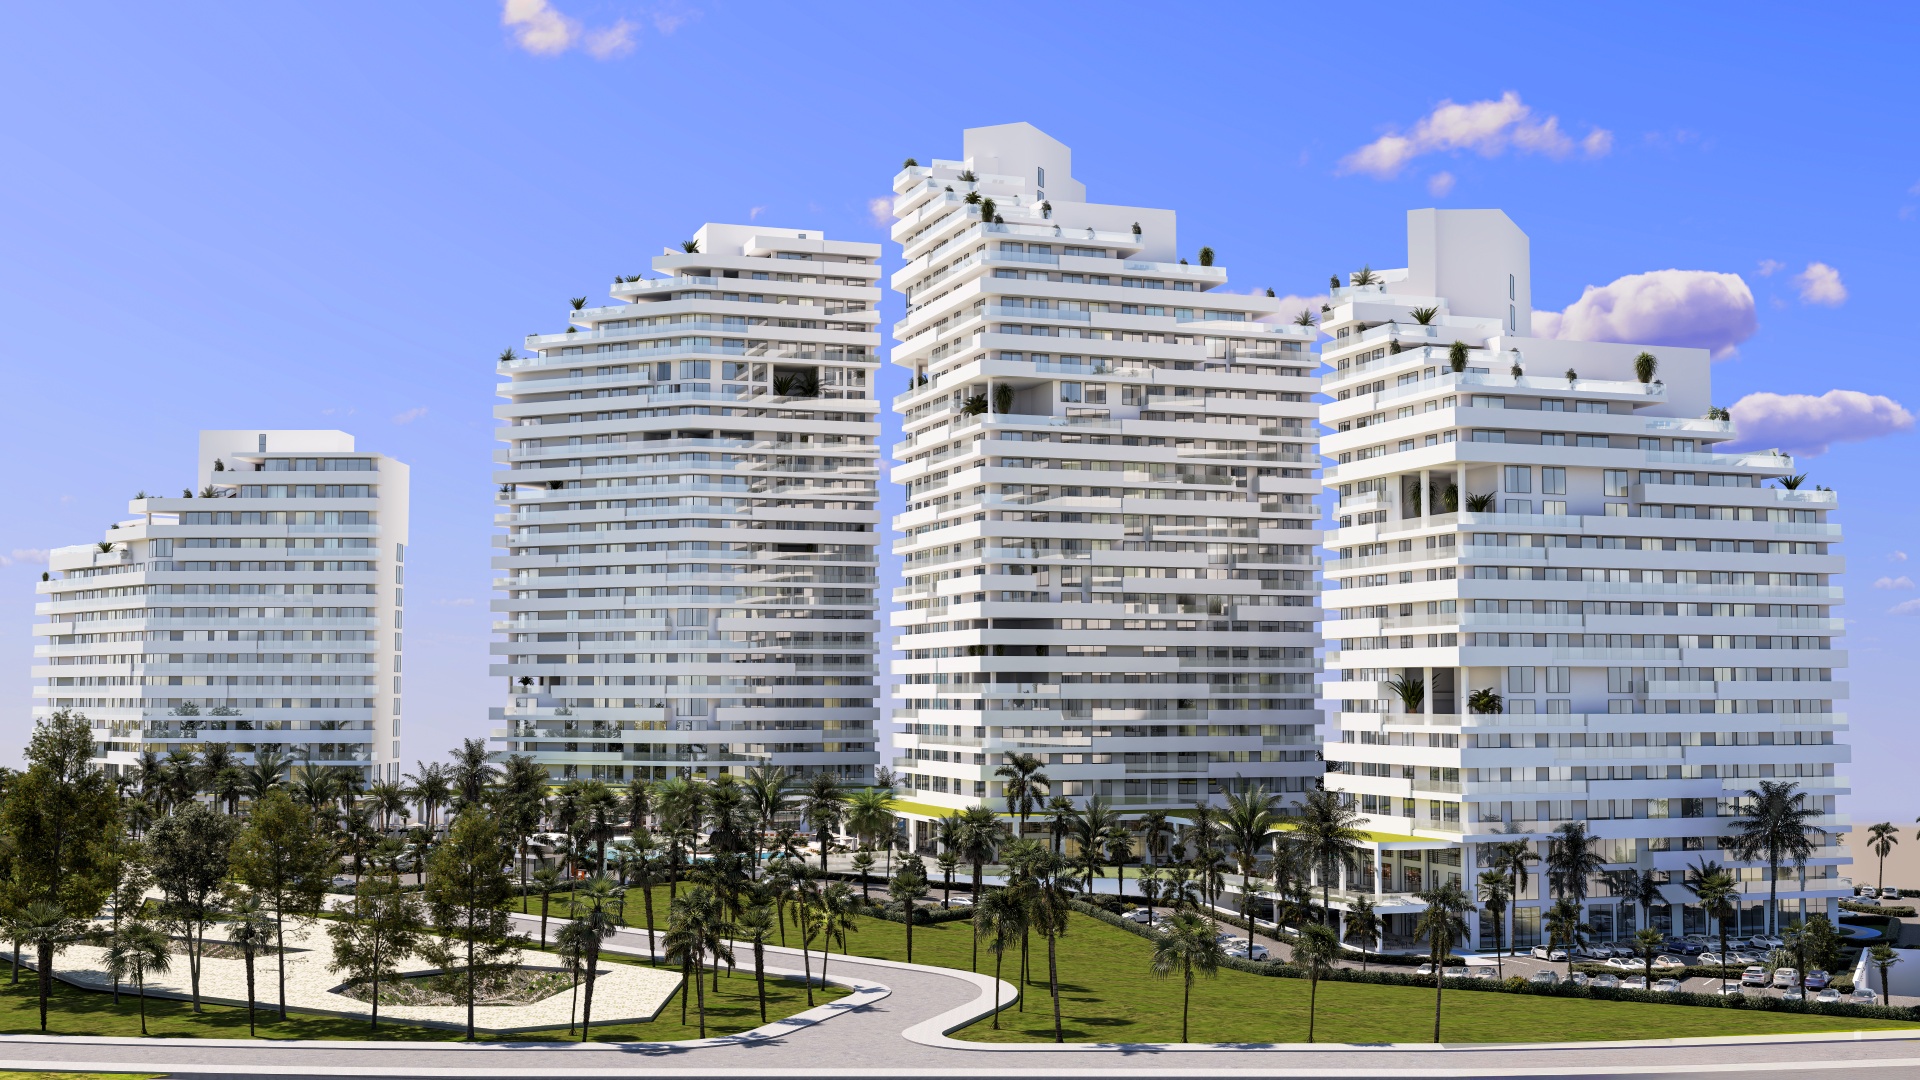
The primary market refers to the first purchase of a property from a developer. This may include a completed apartment, a unit delivered to a developer standard, or a property purchased while still under construction.
“Developer standard” does not always mean the same thing. Typically, the property has basic installations in place and the walls and floors prepared, but the scope of fittings, air conditioning, kitchen, or bathroom finishes depends on the specific project and country.
For the buyer, the schedule is crucial: it determines when the property can be handed over, when finishing works can begin, and, where applicable, when it can be placed on the rental market.
What Does the Secondary Market Mean?
The secondary market refers to purchasing a property from its current owner, regardless of the age of the building. This may be an older property or a relatively new apartment being resold after a short period of use.
One advantage is the ability to inspect the actual property, its views, common areas, and immediate surroundings. Before the transaction, however, the technical condition, ownership history, any encumbrances, and potential renovation costs should be assessed separately. The age of the building alone does not determine whether a property is a good choice.
Advantages and Limitations of Buying From a Developer
The advantages of primary-market properties include new installations, up-to-date energy solutions, building amenities, and the possibility of choosing the layout or finishing standard. In holiday and investment developments, features such as reception services, a swimming pool, parking, rental management, or leisure infrastructure may be relevant, provided they are actually included in the project documentation.
Buying from a developer can be particularly suitable for buyers with a longer time horizon — for example, those planning a second home, a future relocation, or rental after the project is completed. However, a new-build property abroad is not automatically a better investment. Potential delays, the scope of work required after handover, and construction quality should all be taken into account.
What to Verify About the Developer and the Project
Due diligence — a thorough review before purchase — should cover the developer’s experience, the legal status of the land, permits, construction schedule, and the standard of common areas. It is also worth reviewing the payment structure, withdrawal conditions, and documents concerning payment protection.
Mechanisms such as trust accounts, escrow accounts, or guarantee funds do not operate in the same way in every country. MAG World Properties selects projects from developers with at least five years of experience and declared bank guarantees; however, a local lawyer should independently verify the documentation for each specific transaction.
How to Assess the Handover Date and Finishing Costs
A completed property allows you to plan its use sooner, while purchasing during construction may allow payments to be spread according to the project schedule. The handover date should be treated as part of the plan rather than as a guaranteed date from which rental income will begin.
In addition to the asking price, the budget should include finishing, furniture, equipment, community or service charges, insurance, and the period without income before the property is ready for use. The total budget should also include a reserve for currency fluctuations and costs identified in the local documentation.
Advantages and Risks of Secondary-Market Property
One of the main advantages of secondary-market property is the ability to see exactly what you are buying and, often, to receive the keys sooner. Buyers can assess noise levels, natural light, the neighbourhood, the condition of the building, and the actual distance to the beach, city centre, or public transport instead of relying on plans.
A resale property may also offer room to negotiate the price or handover terms. On the other hand, buying a used property requires a more detailed assessment of installations, wear and tear, operating costs, and any obligations associated with the property. A good location does not eliminate the need to verify the documentation.
Technical Condition, Energy Use, and Running Costs
A technical inspection should be carried out before purchase. It is worth checking the electrical and plumbing systems, air conditioning or heating, windows, signs of moisture, insulation, and the condition of common areas.
Ask the seller or property manager for energy bills, information about community or service charges, records of planned building renovations, and documentation of completed upgrades. A lower purchase price may not be advantageous if the property requires costly renovation or generates high recurring expenses.
Ownership Title and Seller Documentation
The land and mortgage register, or its local equivalent, is used to confirm ownership and identify mortgages, easements, claims, and other encumbrances. Access to the register, the scope of information recorded, and the form of ownership may differ significantly between countries.
The seller’s details should be compared with the ownership documents, and the basis on which they acquired the property, any outstanding community charges, and the rules governing the transfer of rights should be verified. An independent lawyer practising in the relevant jurisdiction should review the full set of documents and the draft agreement. A contract should not be signed solely on the basis of a marketing translation or assurances from an intermediary.
Costs, Taxes, and Financing When Buying a Property
The cost of buying a property does not end with the purchase price. Depending on the jurisdiction, the budget may include purchase taxes or transfer fees, notary and legal fees, ownership registration, commission, insurance, furnishings, and ongoing maintenance costs.
On the primary market, taxes and fees may be included in the price or charged separately. On the secondary market, different rules may apply to the taxation of ownership transfers. Rules familiar from Poland should not be assumed to apply in Spain, the United Arab Emirates, Greece, or any other country.
It is advisable to set aside a separate reserve for transaction costs and the first months of ownership. Exact rates, property availability, and financing terms should be confirmed at the time of the transaction.
Mortgage Financing When Buying Abroad
Mortgage financing for non-residents depends on the country, bank, and individual circumstances of the buyer. A bank may assess income, financial history, the source of the down payment, the currency in which the buyer earns, and tax documentation.
Financing an overseas property requires particular attention when income is earned in one currency and loan repayments are made in another. Currency risk means that exchange-rate fluctuations may increase the actual cost of servicing the loan. Before signing an agreement, it is worth obtaining an individual assessment from a bank and an independent financial adviser.
How to Navigate the Overseas Buying Process Safely
The process of buying property abroad varies by country, but following a structured sequence can reduce the risk of overlooking an important step:
- Define your goal and budget. Determine whether the property is intended for living, holidays, rental, or capital diversification, and establish the full budget, including additional costs.
- Choose the country and location. Assess flight accessibility, seasonality, rental regulations, infrastructure, and the form of ownership.
- Compare properties. Analyse the standard, completion date, location, payment plan, and potential running costs.
- Verify the parties and documentation. A lawyer should review the ownership title or project documents, the agreement, any encumbrances, and formal requirements.
- Confirm the reservation and payment terms. Before transferring funds, make sure you understand the refund conditions, deadlines, and payment protection mechanisms.
- Sign the agreement and register ownership. Signing procedures, the involvement of a notary, and registration requirements vary between jurisdictions.
- Take possession and plan property management. For an investment property, it is worth establishing the arrangements for rental, maintenance, and cost reporting.
Expert Support and the Next Step
A real estate adviser can help translate your purchase objective into the choice of country, location, and project. Local specialists can then assist with documentation and coordination with lawyers, banks, developers, and ownership registration authorities.
At MAG World Properties, we help clients analyse several suitable jurisdictions, compare verified projects, and coordinate transactions with local lawyers. The agency’s services are paid for by developers, so the investor does not pay a commission. Providing your budget, purchase objective, and preferred location is enough to begin a structured analysis.
How to Choose the Right Market for Your Goal
The primary market may be more suitable for buyers looking for modern standards, amenities, personalisation options, and a longer project timeline. It is also a natural starting point for those interested in pre-launch developments or purchasing a property for future rental.
The secondary market may be a better fit when a completed property, a specific location, and immediate use are the main priorities. In both cases, a property investment requires an analysis of the country, city, ownership model, total costs, and exit strategy — in other words, what you intend to do with the property if your plans change.
The answer to “which market should I choose?” is therefore neither “always primary” nor “always secondary.” When buying abroad, the right market is the one that matches your objective, followed by an independent verification of the specific property and transaction terms.
Frequently Asked Questions
Is a Primary-Market Property Always More Expensive Than a Secondary-Market Property?
No. A primary-market property is not always more expensive than a secondary-market one. The price depends primarily on the location, standard, stage of development, views, infrastructure, and conditions in the local market.
A new-build property may have a higher purchase price but require fewer immediate renovations. A resale property may be cheaper initially but require upgrades to installations, furnishings, or finishes. Compare the full cost of bringing the property to a condition suitable for living or rental rather than looking only at the price per square metre.
What Documents Should You Check Before Buying a Secondary-Market Property Abroad?
Before purchasing a resale property, you should verify the document confirming ownership, entries in the local property register, any encumbrances, and the seller’s legal authority to enter into the transaction. Depending on the country, this may be a land and mortgage register or another type of property register.
It is also worth obtaining information about mortgages, easements, disputes, outstanding community charges, operating costs, and planned renovations to the building. An independent local lawyer should verify the documents before any deposit is paid or agreement is signed. The scope of legal due diligence depends on the jurisdiction.
Can a Foreigner Obtain a Mortgage to Buy Property Abroad?
Yes, a foreign buyer may be able to obtain a mortgage abroad, but availability and financing terms depend on the country, bank, and individual circumstances of the buyer. Some banks provide financing to non-residents, while others may require local residency, a higher down payment, or additional documentation. Banks typically assess income, source of funds, financial history, income currency, and the value of the property. If the mortgage is denominated in a currency different from the buyer’s income, currency risk should also be considered. Specific terms should be confirmed directly with the bank or a licensed financial adviser in the country of purchase.